One Record, Many Rules: What the London Market’s Shared Layer Means for Your Next Renewal
Your client’s risk data does not live in one place. It sits in your agency management system, in the MGA’s
Underwriting is how insurers decide which risks to accept and at what price: risk selection, classification, exposure rating, and the underwriting cycle that swings the market between soft and hard. This section covers underwriting principles, pricing mechanics, AI in underwriting, and loss-control guidance across commercial lines.
Your client’s risk data does not live in one place. It sits in your agency management system, in the MGA’s
Here is the pitch you will hear at your next renewal meeting: underwriting is going agentic. The pricing software lives
A homeowner in Peoria just got 30 days’ notice that their policy won’t renew. The roof has never leaked. Nothing
Short answer: the file. The verified, dated, account-specific record — the loss runs, the signed application, the inspection, the exposure
Updated Nov 1, 2026 — added the free chat-number challenge card, slow-the-number pack, and copilot feed file downloads to this
Updated Nov 1, 2026 — added the free loss cost vintage quick card, vintage check pack, and version verifier bot
Updated Nov 1, 2026 — added the free two-numbers quick card, two-carrier reconciliation pack, and reconcile-it bot book downloads to
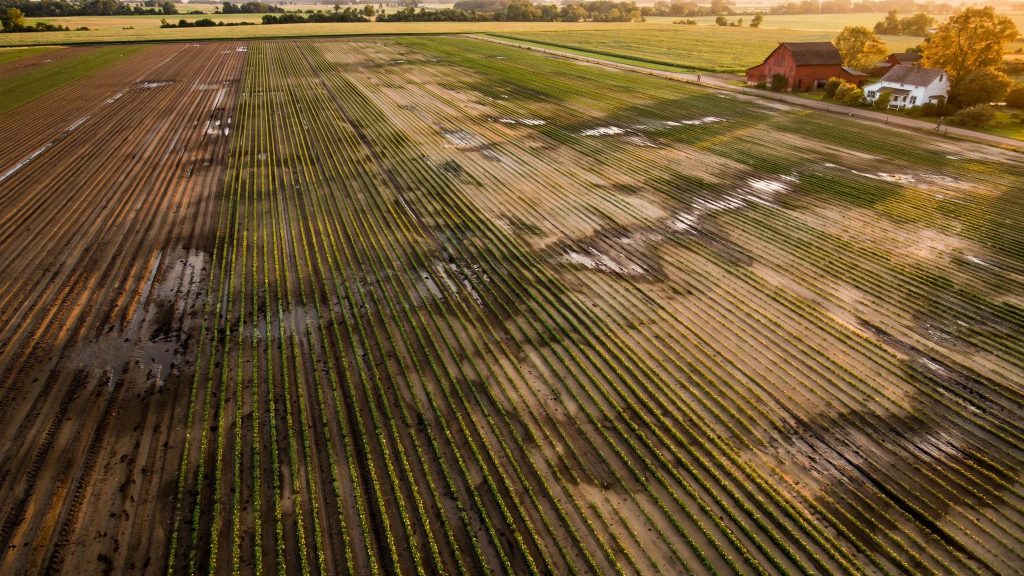
Field-Level Crop Insurance Downloads Prepare Your Ag Clients for Field-by-Field Pricing Ahead of Spring 2027 Field-ready quick cards, fillable winter
Donegal’s October 2026 ZestyAI expansion is one entry in a year of carriers scoring homes from the air. What Z-PROPERTY scores, where it touches the policy, and the five-step correction path to give clients before renewal explains it to them.
Selective’s Q3 2026: underwriting income up 124% to $29.5M and the combined ratio improved to 96.8% while premium fell 7%. What a carrier choosing discipline over growth means for placements, renewals, and new business.
Every experienced underwriter keeps a private ranking of brokers: whose submissions get opened first, whose get to them when there’s
The insurance underwriting cycle is the industry’s recurring rhythm: hard market → transition → soft market → turn, and back