From Cat Model Output to Underwriting Decisions
The model says $40M — now what. How modeled loss becomes rate, retention, and limit decisions, when to override the model, and the questions to ask your carrier.

The model says $40M — now what. How modeled loss becomes rate, retention, and limit decisions, when to override the model, and the questions to ask your carrier.
Never trust one number. How the pros blend vendor models, weight by peril, sensitivity-test key assumptions, and document it all for underwriters and auditors.
The past is no longer the catalog. How climate-conditioned event sets change tail estimates, and how to talk about it at renewal without getting lost in the politics.
Severe convective storms, flood, and wildfire now drive the loss. Why the old models missed them, and what secondary perils mean for your deductibles.
AIR is Verisk’s catastrophe-model line, not a third vendor beside Verisk. Moody’s RMS is the other dominant license. KCC, Cotality, Impact Forecasting, and Florida’s public model are separate families.
Your cat report has a curve, not a number. Here is how to read it: occurrence vs aggregate EP, what a 100-year point really means, and why the tail wags the tower.
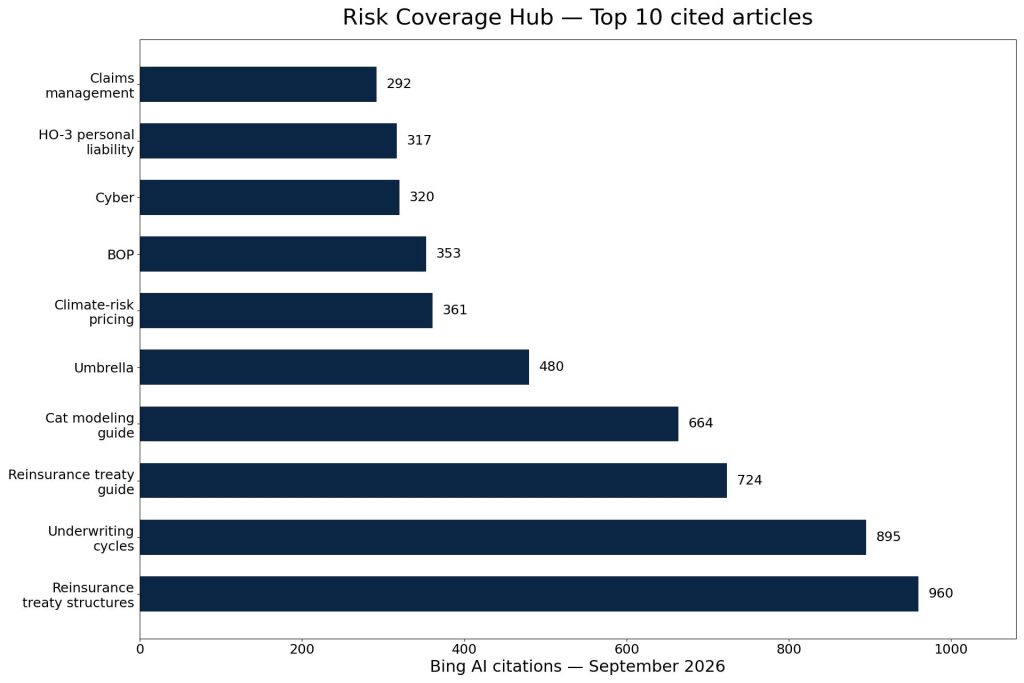
7,683 AI citations in one month vs 124 web clicks. The receipts, article by article.
The 16 HO-3 named perils for Coverage C contents, the Coverage A vs Coverage C asymmetry, and HO-5 as the upgrade.
FNOL duties, notice requirements, and dangerous conditions that can stall a property insurance claim.