HO-3 Named Perils Quick Reference: Why Your Belongings Are Not Covered Like Your House
The 16 HO-3 named perils for Coverage C contents, the Coverage A vs Coverage C asymmetry, and HO-5 as the upgrade.
Property insurance covers physical assets against damage and the income lost while they are repaired: commercial property forms, valuation methods (replacement cost, actual cash value, agreed value), coinsurance, and exclusions. This section covers policy structures, valuation disputes, and the market forces — from catastrophe exposure to construction costs — repricing property coverage.
The 16 HO-3 named perils for Coverage C contents, the Coverage A vs Coverage C asymmetry, and HO-5 as the upgrade.
The 1943 New York Standard Fire Policy still anchors property insurance: ACV valuation minimums, cancellation rules, and the appraisal clause explained.
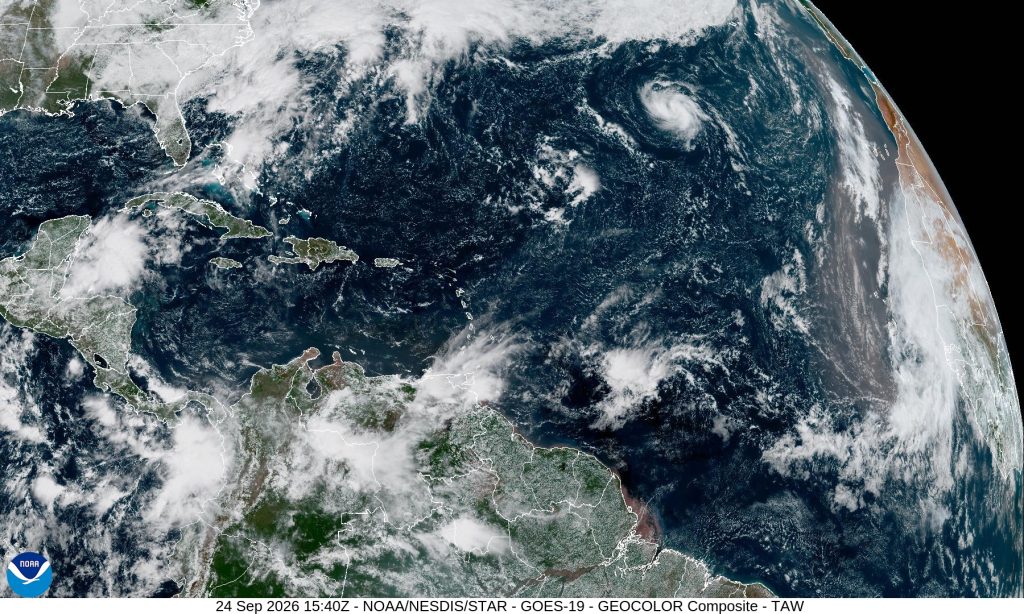
Through Sept. 21, 2026 the Atlantic posted ACE 6.3 — 92% below normal — and zero hurricanes since 1914’s last such date. Treaty and deductible language still assume a storm.
Updated October 1, 2026. The BSR/IICRC S320 public comment period is still open through October 26, 2026 — 25 calendar
Institutional catastrophe risk intelligence briefing for corporate risk managers, property underwriters, and reinsurance brokers for Tuesday, August 25, 2026. NOAA NHC tropical tracking, severe convective storm loss aggregation, and commercial property underwriting takeaways.
Insurance carriers face Scope 3 disclosure requirements reaching into their claims supply chains. The Restoration Carbon Protocol provides per-claim carbon data infrastructure that replaces spend-based proxies for carrier ESG reporting.

Parametric insurance pays when a published index (wind, shake, rain) hits a threshold — not when an adjuster finishes a loss. Speed is the product. Basis risk is the gap vs actual damage. Cat bonds may use the same trigger family. Verified 9 Sept 2026.
Updated October 1, 2026. Direct answer: This page centers on a walkthrough of natural catastrophe modeling for insurance and reinsurance
Watch the Adjuster TV expert video on starting as a claims adjuster, plus key takeaways, timestamps, and 2026 claims management context.
Updated October 1, 2026. Catastrophe models from RMS, AIR, and Verisk translate physical peril science into probabilistic loss estimates insurers
Updated October 1, 2026. Direct answer: Hurricane, earthquake, and wildfire losses are driven by different physics and building vulnerabilities, so
Updated October 1, 2026. Direct answer: Catastrophe portfolio management turns cat model output—PML, average annual loss, and exceedance curves by